en

Call
+8613406350006

The national average seamless pipe price fell 10 yuan/ton to 4,274 yuan/ton this week. Billet prices oscillated weaker, and most mainstream mills trimmed quotes slightly, with downstream buying enthusiasm remaining moderate in September. On the supply side, output stayed at a high level while mill and social inventories drew down slightly. Shandong and Jiangsu billet-rolling mill profits narrowed to 60 yuan/ton and 200 yuan/ton, with blast furnace mill profits continuing to shrink. Against a backdrop of strong supply and weak demand, prices are expected to hold steady with wait-and-see trading and local narrow adjustments next week.
Seamless Pipe Prices: As of September 18, the 108×4.5mm average across 28 major cities stood at 4,274 yuan/ton, down 10 yuan/ton week-on-week — the first weekly decline in several weeks.
Raw Materials: Billet prices adjusted within a range. Shandong billet fell 20 yuan/ton while Jiangsu held flat, widening the north-south gap by 20 yuan/ton to 140 yuan/ton — the "weak north, strong south" pattern persists, with overall oscillating adjustment.
Mill Price Adjustments: According to a Mysteel survey of 30 sample mills, most mainstream mills cut prices slightly by 20 yuan/ton, with only individual mills testing increases of 30 yuan/ton. For overseas buyers, the first broad-based mill price cut in weeks signals that negotiation leverage is swinging back — this is a practical moment to press for better quotes.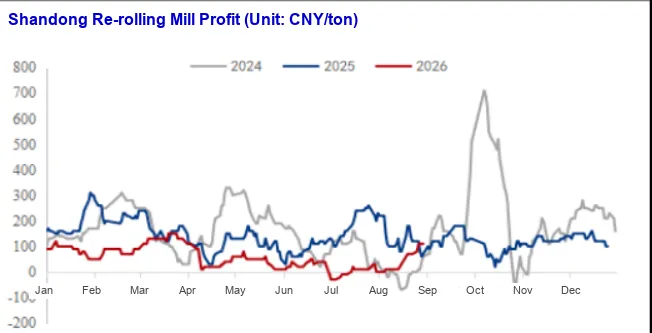
Shandong billet-rolling mill profit narrowed to 60 yuan/ton, down 50 yuan/ton week-on-week; Jiangsu fell to 200 yuan/ton, down 60 yuan/ton week-on-week. Profits are retreating across the board and margin space is shrinking — the recovery pace has slowed, with no near-term driver for further improvement. Squeezed mill margins mean mills have limited appetite to cut deeply, but also little room to push prices higher.
East China seamless pipe prices declined this week. On costs, Shandong and Jiangsu billet prices fell 50–60 yuan/ton, and mainstream Shandong mills followed with a modest 20 yuan/ton cut — relatively restrained. On supply, output kept rising and mill inventory destocked somewhat, though overall inventory levels remain high. On demand, although September is traditionally a peak season, market shipments are running below the same period last year, terminal procurement remains need-based, and distributor inventory turnover is sluggish. East China prices are expected to oscillate weakly next week.
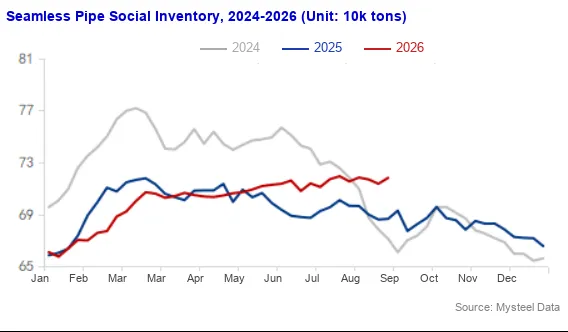
Social Inventory: According to the latest Mysteel survey of 123 distributors, social inventory stood at 711,800 tons, down 2,000 tons week-on-week. With mill ex-factory prices steady, traders remain strongly watchful and inventory slipped slightly.
Mill Inventory: Mill inventory (30 producers, 101 lines) stood at 904,000 tons, down 3,400 tons week-on-week and down 7,200 tons month-on-month; raw material inventory fell to 347,500 tons, down 5,000 tons week-on-week but up 11,300 tons month-on-month. With September demand below expectations, traders and downstream buyers stayed cautious. Mills are planning month-end maintenance and slowing production, and although outbound shipments remain sluggish, inventory pressure has eased somewhat.
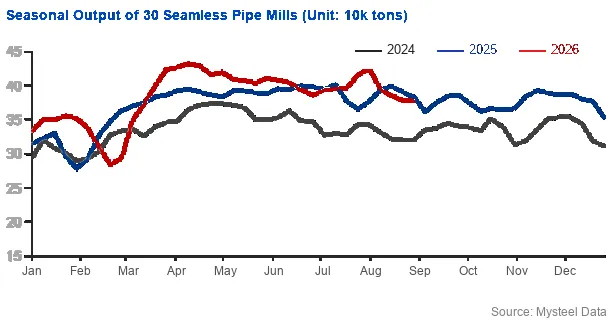
Output reached 407,400 tons, up 4,100 tons week-on-week and up 29,000 tons month-on-month; capacity utilization climbed to 81.7%, up 0.82 percentage points week-on-week and up 5.82 percentage points month-on-month; the operating rate slipped to 72.28%, down 0.99 percentage points week-on-week. Output is running high while shipments stay mediocre, keeping supply pressure substantial — mills are expected to schedule maintenance next week. For overseas buyers, the combination of high output and planned month-end maintenance means near-term availability is ample for order fulfillment, supporting stable lead times on new orders.
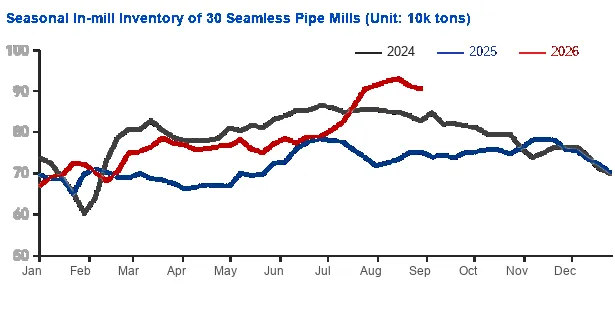
The seamless pipe market remained under pressure this week, with prices continuing to soften modestly and regional performance diverging. On raw materials, billet prices oscillated with north-south divergence, and cost support has weakened. Mills mostly trimmed listed prices slightly with individual probes higher, reflecting a cautious pricing stance. Inventories at both social and mill levels fell slightly, but output remains at a relatively high level and supply pressure has not materially eased. On demand, September's release has fallen short of expectations — traders and downstream buyers are cautious, shipments are mediocre, and distributors are discounting to move cargo. With no clear positive driver and weakening cost support coinciding with soft demand, prices are expected to hold steady with a wait-and-see stance next week, subject to local narrow adjustments.
The national seamless pipe market has tipped back into mild weakness: the average price fell 10 yuan/ton to 4,274 yuan/ton, mainstream mills made their first broad price cuts in weeks, and mill margins narrowed sharply as Shandong profit slid to 60 yuan/ton. Cost support is fading, output remains high at 407,400 tons, and the anticipated September demand surge has not materialized. For international buyers, conditions have turned modestly favorable again — mills are cutting prices, output is ample, and inventory pressure is easing, giving purchasers real room to negotiate. With the market expected to hold steady with only local narrow adjustments, current levels represent a sensible entry point for locking in quotations before any month-end production cuts tighten supply.