en


Call
+8613406350006

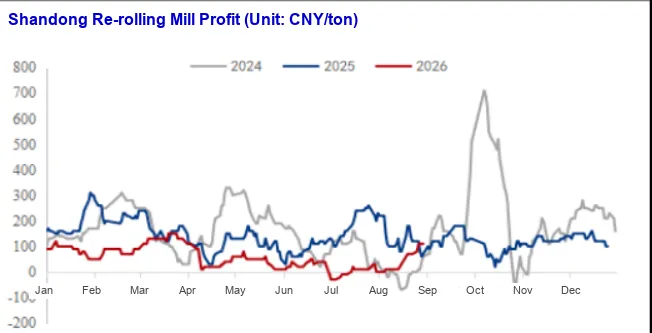
The national average seamless pipe price edged up 1 yuan/ton to 4,284 yuan/ton this week. Billet prices oscillated weaker, and most mainstream mills kept quotes unchanged, with downstream buying enthusiasm moderate in early September. On the supply side, output declined while mill and social inventories both drew down slightly. Shandong and Jiangsu billet-rolling mill profits held flat at 110 yuan/ton and 260 yuan/ton, while blast furnace mill profits contracted notably. With both supply and demand weak, prices are expected to oscillate toward stability next week.
Seamless Pipe Prices: As of September 11, the 108×4.5mm average across 28 major cities stood at 4,284 yuan/ton, up 1 yuan/ton week-on-week — price gains have essentially stalled.
Raw Materials: Billet prices adjusted within a range this week. Shandong billet fell 20 yuan/ton while Jiangsu rose 10 yuan/ton, widening the north-south gap by 30 yuan/ton to 120 yuan/ton — a "weak north, strong south" pattern with widening spreads, overall characterized as oscillating adjustment.
Mill Price Adjustments: According to a Mysteel survey of 30 sample mills, most mainstream mills held prices steady, with only individual mills raising quotes by 100 yuan/ton. For overseas buyers, the pause in broad price hikes opens a short window for confirming quotations at current levels.
Shandong billet-rolling mill profit held at 110 yuan/ton and Jiangsu at 260 yuan/ton, both flat week-on-week. Profit recovery remains underway but has clearly slowed, and further near-term improvement lacks a driving force. Flat mill margins, together with widening room for price negotiation on firm orders, mean buyers currently hold modest but real bargaining power.
Mainstream city prices in East China were flat week-on-week — Shanghai, Nanjing, and Hangzhou saw no adjustment. Sample mill output continued to rise slightly, mill inventory eased week-on-week, and market inventory dipped. On the demand side, peak-season demand has shown no clear improvement and order books remain weak, leaving prices drifting downward. Without a demand recovery across the "Golden September–October" period, prices will remain easier to fall than to rise in the short term. East China prices are expected to consolidate in a range near term.
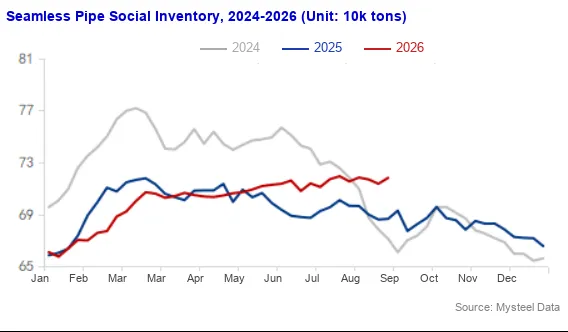
Social Inventory: According to the latest Mysteel survey of 123 distributors, social inventory stood at 713,800 tons, down 4,200 tons week-on-week. With mills holding ex-factory prices steady, traders remain strongly watchful on the outlook and inventory declined slightly.
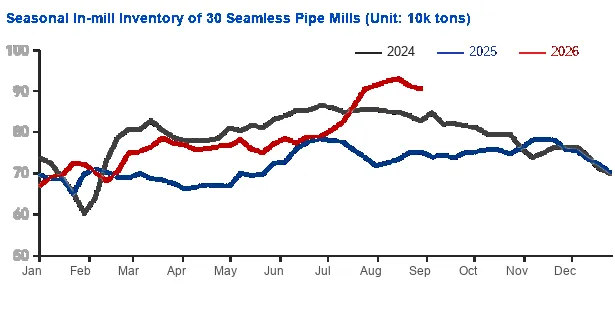
Mill Inventory: Mill inventory (30 producers, 101 lines) stood at 916,700 tons, up 11,500 tons week-on-week but down 6,500 tons month-on-month; raw material inventory rose to 357,200 tons, up 17,900 tons week-on-week. September demand falling short of expectations kept traders and downstream buyers cautious, slowing mill outbound shipments and pushing inventory up.
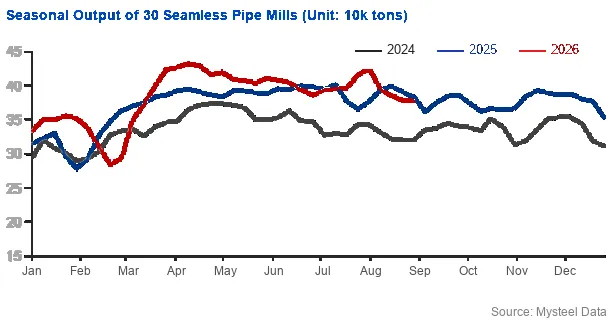
Output reached 385,500 tons, up 7,800 tons week-on-week but down 8,900 tons month-on-month; capacity utilization was 77.3%, up 1.57 percentage points week-on-week; the operating rate held at 68.32%, down 6.93 percentage points month-on-month. With mill maintenance largely concluded, output rose while shipments stayed mediocre, keeping supply pressure considerable. Production is expected to remain at normalized levels next week.
September has brought only moderate downstream buying, leaving both supply and demand weak this week. Mill and social inventories drew down slightly, billet-rolling mill profits held flat, blast furnace mill profits contracted notably, and the pace of profit recovery has slowed. Market watchfulness is thick and room for price negotiation on firm orders has widened. Notably, Shanxi Jianbang's steel pipe project is about to begin trial rolling — the new line will bring fresh supply to the seamless pipe market and may disrupt regional supply-demand structures, though its near-term direct impact remains limited. With cost support still present but upward drivers insufficient, "Golden September" expectations continuing to be disproven by weak reality, and Jianbang's ramp-up adding a supply-side variable, national seamless pipe prices are expected to oscillate toward stability next week as the market stays on the sidelines.
The national seamless pipe market has plateaued: the average price rose just 1 yuan/ton to 4,284 yuan/ton, mills stopped raising quotes broadly, and both supply and demand remain weak. Cost support persists but upward momentum is exhausted, and September demand has failed to deliver the anticipated peak-season boost. For international buyers, this is a modestly favorable setting — price increases have paused, negotiation room on firm orders has widened, and a major new mill project adds future supply. With downside limited by costs and upside capped by weak demand, prices are expected to hold in an oscillating, stable range — a reasonable moment to finalize quotations for orders in the pipeline.